35 Money Mistakes You Need to Stop Feeling Guilty About
Some links may be affiliate links. We may earn a commission at no extra cost to you. View our full disclosure.
Somewhere along the way, having a normal financial life started to feel like failing a test nobody ever handed you the answer key for. Buy the coffee, feel a twinge.
Skip the side hustle, feel behind. Carry a student loan into your thirties, feel like everyone else already figured it out.
None of that guilt is doing you any favors, and most of it is not even earned. A lot of what gets filed under “money mistake” is just a normal, reasonable choice wearing a guilty conscience it never should have picked up.
This list runs through thirty-five of the most common ones, starting with the small everyday guilt trips and working up to the big one hiding underneath all the others. Some of these really do deserve a second look, and this list will say so plainly when that is the case.
Most of them do not. Most of them are just what a real financial life looks like, lived by a real person who does not have a spreadsheet for every decision.
Consider this permission to stop treating every dollar as a referendum on your character. Here is where the guilt trip actually ends.
35. Turning Down a Destination Wedding Invitation
A friend gets married three states away and suddenly you owe flights, a hotel, a gift, and a suit that fits. Saying no to that invitation feels like saying no to the friendship. It is not the same thing, even though it feels like it in the moment.
Weddings have quietly become one of the more expensive social obligations a person can get roped into, right up there with the money conversation couples keep avoiding. Declining one because the math does not work is a budgeting decision, not a character flaw.
The upshot: Missing a wedding you cannot afford does not make you a worse friend, it makes you someone who knows what a plane ticket costs.

34. Skipping the Extended Warranty at Checkout
The checkout screen asks if you want to protect your purchase and something in the back of your brain says you probably should. Most of the time the answer is no.
Extended warranties are priced to make money for the store, not to make you whole, which is part of why they show up on lists of “normal” expenses frugal people refuse to pay. A little research on the actual failure rate of most appliances usually settles the guilt fast.
**Declining the add-on protection is not the same as declining to be careful with money, it is one of the more careful things you can do at that register.**
33. Spending More on Vet Bills Than the Math Says You Should
A pet gets sick and suddenly the bill is a number nobody budgeted for. Paying it anyway, even when it stretches things thin, is not the reckless part of the story.
The guilt usually shows up afterward, doing math on what that money could have done elsewhere. That comparison rarely accounts for what the animal is actually worth to the household, which is part of why it rarely makes any list of habits people good with money actually skip.
32. Letting Insurance Premiums Auto-Renew Instead of Shopping Around
Every renewal notice is a reminder that you were supposed to shop around this year and did not. Life got busy, the notice got filed, and the same policy renewed at a slightly higher rate.
Rate shopping really can save a real amount over a year, which is exactly the kind of thing that belongs on a list of ways people are quietly cutting their monthly bills. Not doing it does not erase your gains from every other smart call you made that year.
Worth remembering: One skipped errand does not undo a year of otherwise solid decisions, it just leaves a little money on the table until the next renewal notice shows up.
31. Buying Lunch at Work Sometimes
The math on brown-bagging every single day is real, and it is also not how most people actually live. Some weeks there is no bread in the house, no time to pack anything, and buying lunch is costs way less than most people think than the guilt makes it feel.
The problem was never the occasional twelve-dollar lunch. It was treating every one of them as a moral failure instead of a normal cost of having a job and a busy week.
**A few bought lunches a month are not the reason a savings account is stuck, they are just lunch.**
30. Not Reading Every Personal Finance Book
There is a version of financial guilt that has nothing to do with spending and everything to do with homework you never did. The unread books pile up, the podcasts stay unplayed, and it feels like a personal failing.
Most of what those books teach boils down to a handful of repeated ideas dressed up in new language each time. Skipping the reading list does not mean skipping the fundamentals.
29. Not Knowing Your Credit Score to the Exact Point
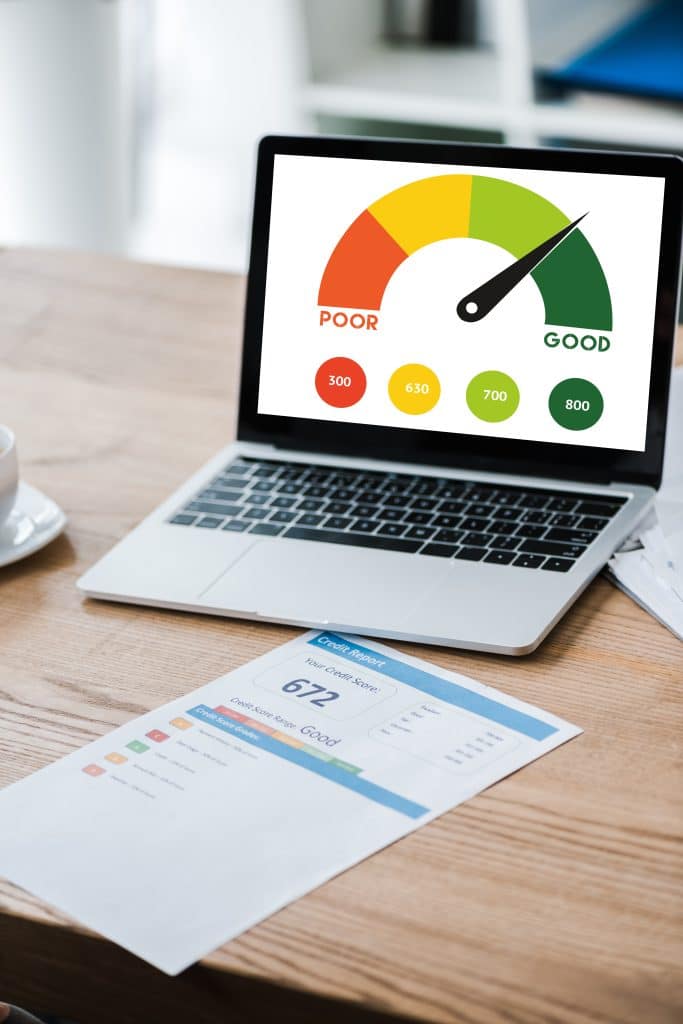
There is a difference between having no idea what your credit looks like and not knowing the number down to the single digit. The second one is fine, and honestly it is close to a “money rule” that turns out to be a myth that you need to.
Knowing the general range, good, fair, needs work, is usually all that actually changes a decision. Checking the exact number monthly does not move it any faster.
Net effect: The range matters for loan applications. The exact figure mostly matters for peace of mind, and that is optional.
28. Retail Therapy in Small, Contained Doses
Buying a small something after a rough week gets talked about like it is the first domino in a financial collapse. For most people it is more like a pressure valve than a habit.
The version that actually causes damage is unlimited and untracked. A twenty-dollar treat with a clear ceiling is a completely different animal.
**A contained splurge is not the enemy of a budget, an uncontained one is, and those are two very different things.**
|
You might also like
16 Ways People Make Extra Money During the Holidays →
|
27. Buying Store-Brand Everything Except Your Few Favorites
Frugal advice tends to be all or nothing, buy the store brand or admit you are wasting money. Real households run a hybrid system, “cheapskate” tricks that actually work on most things while keeping a short list of name-brand exceptions.
That short list usually has a real reason behind it, a texture that actually differs, a taste that actually matters to someone in the house. Keeping it is not a lapse in discipline.
26. Ordering Takeout on Your Worst Weeknights
There is a specific kind of guilt that shows up when the app confirms the order and you know exactly how many delivery fees you are paying without realizing it. Most of the time it is not the fee that is the problem, it is the story attached to it.
A takeout order on the night everything went wrong is not a budgeting failure. It is a person making a reasonable trade between money and bandwidth on a day that had none left.
Where this lands: The occasional rough-night order is a coping tool, not a pattern, and the two deserve different reactions.
25. Spending on Hobbies That Make Nothing
Somewhere along the way, hobbies started needing to justify themselves financially or become side hustles. A hobby that produces nothing but enjoyment is doing exactly what it is supposed to do.
The guilt usually comes from comparing hobby spending to investing, which is not a fair fight. Money spent on something that genuinely recharges a person is not money wasted, it is money doing a different job.
**Not every dollar has to grow, some of them are just there to make a Tuesday better.**
24. Having “Fun Money” With No Justification
A set amount of money that exists purely to be spent on whatever, with no receipts required, sounds irresponsible on paper. It is actually one of the “bad” money habits that are actually fine once you look at how it actually functions inside a working budget.
The whole point of a fun money line item is that it does not need justifying. That is what separates it from every other category on the spreadsheet.
23. Giving Money to Family, With Limits
Helping a family member out financially, within reason, gets treated like a betrayal of your own future. It is one of the more human things a person can do with money.
The honest complication here is real, though. Help that turns into a repeated, unspoken expectation stops being generosity and starts becoming a leak with no bottom, and that version does deserve a hard conversation instead of quiet guilt.
The math: Occasional help with a clear limit is generosity. A standing, unspoken obligation is a different problem, and it is fine to name that difference out loud.
22. Taking the Occasional Vacation While in Debt
The strict version of financial discipline says no travel until every debt is gone. That is a fine rule for some households and a completely unworkable one for others, which is part of why the worst possible time to make a big purchase is more complicated than a single rule can capture.
A modest, planned trip while carrying a manageable balance is not the same as financing a vacation you cannot remotely afford. Context does most of the moral work here.
**Debt with a payoff plan and a trip with a real budget can coexist, they are not automatically in conflict.**
21. Buying New Instead of Used, Sometimes
The frugal-minded corner of the internet leans hard on buying used, and there is a lot of truth in the idea of things smart shoppers always buy secondhand. That does not mean buying new is always wasteful.
Some items genuinely wear differently used, mattresses and certain safety gear being the obvious ones. Choosing new for the right item is a decision, not a defeat.
20. Paying an Annual Fee for a Credit Card You Actually Use
A card with a fee attached triggers an automatic assumption that a free version would obviously be smarter. Sometimes the math actually runs the other way.
If the perks and rewards genuinely exceed the fee, and they get used rather than ignored, the fee is doing its job. Paying it is not a sign the card is winning.
The upshot: A fee that pays for itself is not a mistake, it is a line item that earns its keep, and it is worth checking the math once a year instead of assuming.
19. Ignoring the Market for Months at a Time
There is an expectation floating around that a responsible person checks their portfolio constantly. In most cases, checking less often is the more disciplined behavior, not the lazier one.
Long stretches of not looking usually mean fewer panicked decisions during dips. The guilt over not paying attention is often backward.
Worth remembering: Ignoring the daily noise on purpose is a strategy some professionals actually recommend, not a lapse in responsibility.
18. Not Picking Individual Stocks
Somewhere a coworker mentions picking a stock that tripled and the guilt kicks in about being too boring with money. Boring, broad, diversified investing is not a lesser strategy, it is the one that shows up as sound in most long-term comparisons.
This article is not financial advice and is not making a specific recommendation either way. It is worth talking through your own approach with a qualified professional rather than a listicle.
Myth vs. Reality: The Halfway Gut-Check
Myth: every one of these “mistakes” is quietly sabotaging your future.
Reality: most of them are neutral choices that only look like mistakes next to an imaginary version of yourself with unlimited discipline and zero bad weeks.
|
Worth It or Not
18 January Money Moves That Set Up Your Whole Year
|
That imaginary version does not exist for anyone, including the people who seem to have it all figured out on the outside.
17. Not Having a Side Hustle
Everyone online seems to have a side gig, a shop, or a newsletter, which makes a single full-time job feel like underachieving. There are plenty of ways to make extra money without a side hustle, and choosing not to take any of them on is a valid choice too.
A full day of work followed by an evening of rest is not a wasted opportunity. It is what a job is supposed to leave room for.
Worth remembering: A second income stream is a bonus for people who want the trade-off, not a requirement for being financially responsible.
16. Spending Real Money on a Good Mattress
A mattress is one of the few purchases where the cheap option genuinely costs more over time, in sleep, in back pain, and eventually in a second mattress. Spending real money here is closer to an investment than an indulgence.
The guilt over the price tag usually fades within the first few nights of actually sleeping better. That is not a coincidence.
**Some purchases are worth the sticker shock because you use them for roughly a third of every single day.**
15. Paying for Convenience When You’re Busy
Paying someone else to do the thing you could technically do yourself gets filed under laziness more often than it should. Time is worth something too, and a genuinely packed week is a real reason to spend money buying some of it back.
The trade only stops making sense when the convenience becomes constant and the underlying time crunch never gets addressed. Occasional convenience spending during an actually busy stretch is just a reasonable trade.
14. Keeping One Splurge Category That Outsiders Would Judge
Everyone has one category where the spending would look excessive to a stranger looking in from outside. Concerts, collectibles, a specific hobby, it does not matter which one it is.
As long as the rest of the budget is intact, one protected splurge category is not a problem. It is usually the thing keeping the rest of the discipline sustainable.
Net effect: A single guarded indulgence, fully funded and not hidden from a partner or a budget, tends to make everything else easier to stick to.
13. Buying Your Daily Coffee
This is the single most repeated line in personal finance content, and it has been picked apart enough times that what coffee habits actually cost over a year usually turns out to be smaller than the myth suggests. It is real money over a year, but it is rarely the difference between a good and bad financial life.
The habit matters far less than what happens to the money that is not spent on coffee. Cutting the coffee without redirecting the savings anywhere accomplishes almost nothing.
**A daily coffee habit is a preference with a price tag, not a moral failing, and it stopped being interesting advice a long time ago.**
12. Leasing a Car, In Some Situations
Leasing gets treated as the financially illiterate option next to buying outright. For someone who wants predictable payments, avoids repair headaches, and swaps vehicles often, it can genuinely be the better fit.
The math depends heavily on how many miles get driven and how long the vehicle gets kept. There is no single right answer that applies to every household.
11. Spending More on Housing Than the Old Rules Allow
The old rule of thumb about housing costs staying under a fixed share of income was built for a very different housing market. In a lot of regions, following that rule to the letter now means never living anywhere reasonable.
Spending somewhat above the old benchmark, on purpose, with the rest of the budget adjusted to match, is a rational response to a changed reality. It is not automatically the reckless choice the old rule implies.
Where this lands: A rule built decades ago does not automatically apply to a market it never accounted for, and it is worth checking your regional numbers before assuming you have failed it.
10. Not Buying a Home in Your Twenties
Homeownership got positioned as a milestone with a deadline attached, and missing that deadline gets treated like falling behind. Renting through your twenties while building other savings is a completely legitimate path.
Buying too early, before income and location are stable, tends to cost more in the long run than waiting. A delayed purchase is not automatically a mistake.
**There is no expiration date on becoming a homeowner, and buying at the right time beats buying on schedule.**
9. Using a Credit Card for Everything
Putting every purchase on a card, groceries, gas, the occasional coffee, gets treated like a debt problem waiting to happen. If the balance gets paid off in full every month, it is mostly a rewards and tracking strategy in disguise.
Here is the honest exception worth naming directly: if that balance is not being paid off in full, the interest is real and the guilt has a legitimate reason behind it. That distinction changes everything about whether this belongs on a guilt-free list at all.
8. Having Student Loans in the First Place
Carrying student debt into your thirties and forties gets framed as a personal financial planning failure. For most borrowers, it was a decision made at eighteen with very little context about what the number would eventually mean.
The debt is a fact to manage, not a verdict on a person’s judgment at any current age. Paying it down steadily is the responsible part, not the existence of the balance itself.
The math: A loan taken out before you could legally rent a car is not evidence of poor adult decision-making, it is evidence of being a teenager.
|
You might also like
17 Things That Actually Cost Less Than They Did 40 Years Ago →
|
7. Paying Off a Low-Interest Loan Slowly, On Purpose
Debt avoidance culture treats every unpaid loan as an emergency, regardless of the interest rate attached to it. A loan with a genuinely low rate, paid on schedule while other money goes toward higher-return goals, is a defensible strategy rather than a delay tactic.
The math is worth checking for your own situation rather than assuming, and it varies by loan type and rate, so this is not a blanket recommendation. It is simply not automatically wrong to keep low-cost debt around longer than the minimum.
6. Keeping Money in a Boring Savings Account
Investment content makes an ordinary savings account look like money sitting still and losing ground. An emergency fund, a near-term goal, money you cannot afford to see drop in value, all belong exactly where boring and stable beats growth.
Not everything needs to be invested for the account to be doing its job right. Liquidity and safety are the whole point of that particular bucket.
**Boring is a feature in a savings account, not a bug, and it is doing exactly what it was built to do.**
5. Carrying a Mortgage Into Retirement
The old picture of retirement includes a fully paid-off house, and not matching that picture feels like falling short. A low, fixed mortgage rate carried into retirement, while other money grows elsewhere, is often the stronger financial position, not the weaker one.
This is a personal call that depends heavily on your own rate, timeline, and comfort with debt, and it is worth running by a qualified professional rather than a general rule. It is not automatically a red flag on its own.
The upshot: A paid-off house feels safer emotionally, but a low-rate mortgage carried strategically is not the financial failure it is often made out to be.
4. Not Maxing Out Every Retirement Account
Contribution limits get treated like a target everyone should be hitting, when in reality most households are nowhere close, and that is typical rather than alarming. Reviewing contributions once a year, similar to money moves people wish they had made sooner, matters more than hitting an arbitrary ceiling every single year.
Contributing something consistently beats contributing the maximum sporadically or not at all. The habit matters more than the headline number.
**Not maxing out an account is the default for most people, not the exception, whatever the online calculators imply.**
3. Starting to Save “Late”
Compound interest charts love to show the mythical twenty-two-year-old who started investing immediately and retired a millionaire on autopilot. Most real people start later, for real reasons, job instability, debt, family needs, and that timeline is not a personal failure.
Any chart showing growth over decades is a hypothetical illustration, not a prediction or a guarantee for any individual’s situation. Starting at thirty-five or forty-five still works, it just works on a different schedule.
2. Not Following a Line-Item Budget
A detailed, tracked-to-the-dollar budget works well for some people and feels like a second job for everyone else. A simpler system, broad categories, a monthly check-in, still counts as budgeting.
The goal was never the spreadsheet itself. It was knowing roughly where the money goes and not being surprised at the end of the month.
Worth remembering: A rough system you actually maintain beats a detailed one you abandon after three weeks, every time.
1. Making Money Mistakes at All
This is the one underneath all the others. Somewhere along the way, personal finance content started implying that a genuinely responsible adult makes zero missteps with money, ever, and everyone else is behind.
That standard has never actually existed for anyone, including people whose finances look put together from the outside. Every real financial life includes a car bought at the wrong time, a year with no savings progress, a debt that took longer than planned to clear.
Those moments are not evidence of failure, they are just what building a financial life actually looks like, the same way the small leaks quietly draining an account do not erase everything a household is doing right elsewhere. The goal was never a perfect record.
The goal is a general direction that trends the right way over years, not months, with room for the bad stretches. A single mistake, or a dozen of them, does not cancel that out.
**A financial life with a few mistakes in it is not a broken one, it is just a normal one, and that is worth actually believing instead of just reading.**
None of This Makes You Bad With Money
If there is a short version of this whole list, it is this: guilt is not a financial strategy, and most of these thirty-five things were never actually mistakes in the first place.
A handful of them genuinely deserve a closer look, carrying a credit card balance you are not paying off, letting a family loan turn into a standing unspoken expectation, insurance you have not shopped in years. Those are worth an honest hour with your own numbers.
The rest of the list is just the normal texture of an adult financial life. Lunch bought on a bad week, a splurge category that makes the rest of the budget bearable, a mattress that cost more than it should have and was worth every dollar of it.
None of that adds up to bad money management. It adds up to a person living a life instead of running a spreadsheet.
Start with the two or three items on this list that actually cost you real sleep, and let the rest of the guilt go. That alone will do more for your financial life than another year of quiet self-criticism ever did.